Kolan Review: Is the Former Hurupay a Safe Place to Get Paid in Dollars?
Kolan (formerly Hurupay) reviewed: how its USD, EUR and GBP account details and USDC balance work, what receiving and spending cost, the business-only Visa card, the freeze and confiscation terms, user complaints and who should skip it.
Last updated 27 October 2026
Best for
Freelancers and remote workers outside the UK, especially in Nigeria, Kenya, the Philippines and Argentina, who are paid by US clients or platforms such as Upwork and Gusto, want to hold earnings in dollars, and will move money out soon after it lands.
A useful pipe, not a place to keep savings. Kolan gives you US, euro and sterling account details, settles everything into USDC and lets you withdraw that USDC for free, which beats many local routes for getting paid from abroad. Fees bite at the small end: a $50 ACH payment loses a flat $2 and an $80 wire loses $32. The bigger issue is trust. The website footer talks about FDIC insurance, but the Terms of Service say your funds are USDC and not insured, and section 19 lets Kolan confiscate account funds indefinitely without warning. Trustpilot reviewers report exactly that kind of freeze. There's no sign-up bonus. If you join, test with a small payment, withdraw regularly and never park more than you could wait months for.
Pros
- USD, EUR and GBP receiving details in one app, built for people paid by foreign clients
- Payroll and platform payments (Upwork, Gusto, Payoneer, Fiverr, Rippling) have no per-payment cap
- Free withdrawals to USDC or USDT, plus local payouts in currencies such as NGN, KES and PHP
- Earnings stay in dollars instead of a weakening local currency
- A virtual Visa card that spends the same balance and adds to Apple Wallet
- Same company since 2024: Hurupay Inc. only changed the brand in August 2026
Watch-outs
- No sign-up bonus for joining through an invite
- The terms say balances are USDC with no FDIC or other deposit insurance, despite the FDIC wording on the website
- Section 19 lets Kolan cancel access to or confiscate funds without warning or reasons
- Flat fees hit small payments: $2 by ACH and $32 by wire under $100
- The card is for business use only and costs up to 6% on foreign-currency purchases abroad
- Email-only support, slow identity checks and reports of accounts paused after deposits
Current related offer
Kolan offer pageReferral links: BitBoni may earn a commission when you sign up.
Provider
Kolan
Join Kolan (formerly Hurupay) through this invite for USD, EUR and GBP account details, a virtual Visa card and crypto trading in one app; there is no sign-up bonus. Balances settle in USDC, aren't deposit-insured, and Kolan's terms let it freeze account funds without warning.
Requirement: Sign up through the invite and pass identity checks; incoming payments start at $5 by ACH or $50 by wire, up to $4,999 each
KYC countries: Open everywhere except 15 countries
Medium10-15 minutes to install and sign up; identity checks can take days or weeksPayout No sign-up bonus to pay out. Incoming payments settle into your Kolan balance as USDC; withdrawals to USDC or USDT are free, and local bank or mobile-money payouts carry partner fees shown in the app.
Verified 27 October 2026
Full claim instructions are on the Kolan offer page.
What Kolan is
Kolan is the app Hurupay Inc., a Delaware company based in San Francisco, has run since 2024. It announced the new name on 4 August 2026 and kept the same company, team, contracts and accounts; legal documents now say "Kolan, a DBA of Hurupay Inc." The pitch is one app for money earned across borders: receive US dollars, euros and sterling, hold the balance in stablecoins, spend with a virtual Visa card, withdraw locally, and trade crypto, memecoins, perpetual futures and prediction markets from the same balance.
Kolan isn't a bank and holds no banking licence of its own. It opens and runs accounts with partners on your behalf: a US account for incoming dollars and a crypto account with an exchange. Its guides are written for freelancers in Nigeria, Kenya, the Philippines, Argentina, Pakistan and Spain, though it publishes no list of supported countries. Sign-up checks your country, and sanctioned countries and countries that ban crypto are excluded.
Where your money sits
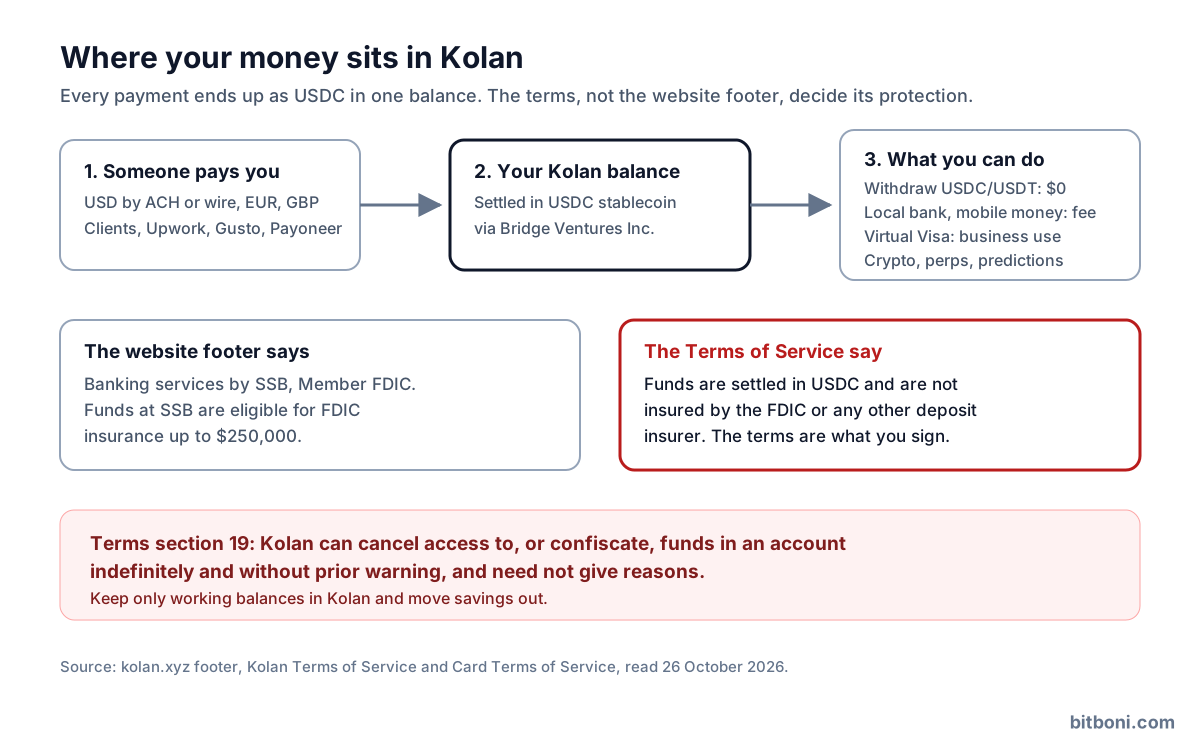
This is the part to read twice. The footer on kolan.xyz says banking services are provided by SSB, Member FDIC, and that funds deposited at SSB are eligible for FDIC insurance up to $250,000. The Terms of Service you agree to say something different: banking services come through Bridge Ventures Inc., funds on Kolan are settled in USDC stablecoin, and they are not insured by the FDIC or any other deposit insurer. The terms are the contract, so treat your Kolan balance as USDC held through a fintech, not as a bank deposit.
USDC is a dollar stablecoin issued by Circle. It tracks the dollar closely, but it isn't government-insured money, and you rely on Kolan and its partners to let you move it. That reliance is where section 19 matters: Kolan can cancel access to, or confiscate, any funds in an account indefinitely, without prior warning, and may decline to say why.
Getting paid: US dollars, euros and sterling
Your US details accept ACH and wire transfers from a personal US bank account, PayPal or Wise, and from employers and platforms. ACH payments start at $5 and wires at $50, and a single payment can be up to $4,999; payroll and platform payments from Gusto, Upwork, Rippling, Fiverr or Payoneer have no limit, and you can email Kolan to ask for a higher limit on the rest. A payment that arrives without your full, correct account details is cancelled, so copy the details exactly as the app shows them.
Euro and sterling details take SEPA, SWIFT and Faster Payments. Kolan doesn't publish fees or limits for them, so check the deposit screen in the app before you hand the details to anyone. Everything that lands converts into the same USDC balance.
What it costs: a worked example
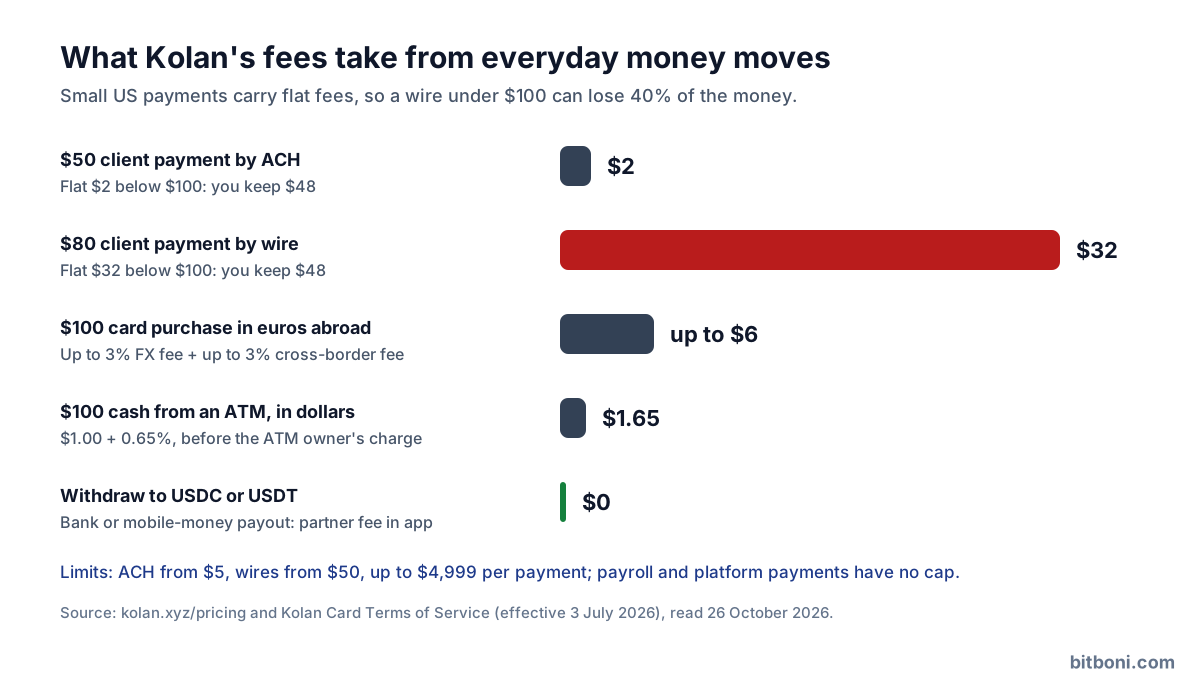
Kolan's published fees are flat at the small end. An ACH payment under $100 costs $2, and a wire costs $30 more than ACH, so a wire under $100 costs $32. A client paying $50 by ACH leaves you $48; the same client paying $80 by wire also leaves you $48, a 40% cut. If a payer offers a choice, take ACH, and ask small clients to batch invoices. Kolan doesn't publish the ACH fee from $100 upward; its pricing calculator shows it for your amount.
Getting money out costs nothing in USDC or USDT. Payouts to a local bank or mobile-money account go through partners whose fees depend on the route, and the conversion uses the rate shown in the app at the time; Kolan's pricing page quotes indicative rates into NGN, KES, GHS, ZAR, PHP, ARS and CAD, last updated in August 2026. Kolan doesn't publish its fees for crypto trading, perps or prediction markets.
The Kolan virtual Visa card
You can create a virtual Visa card in the app and add it to Apple Wallet. Third National issues it under licence from Visa, and it spends against your Kolan balance: the spending limit equals the collateral you hold for it, and Kolan can lower that limit at any time, down to $0. The card carries a 0% interest rate, but anything left unpaid for one calendar day can trigger liquidation of your collateral.
Purchases in a currency other than dollars cost up to 3% in FX, and purchases outside the US up to another 3% cross-border, so a $100 euro purchase in Europe can cost $6. ATM withdrawals cost $1.00 plus 0.65%, with $0.60 for balance checks and declines. Two clauses matter before you rely on it: the card terms say it is for business use only, not personal, family or household spending, and they ask you to attest that you weren't solicited for the card. Treat it as a way to pay for work tools and subscriptions, not as your everyday debit card.
Crypto, perps and prediction markets
The same balance can buy crypto and trending memecoins, open long or short positions on perpetual futures, and trade prediction markets on sport, elections and prices. These are speculative products: perps use leverage and can be liquidated, prediction positions can go to zero, and memecoins are among the most volatile assets there are. Kolan's terms put every trading loss on you.
UK residents and citizens can't use the perps or prediction markets at all; the terms also exclude anyone in a sanctioned country or a country that bans crypto. If you're there to get paid, you can ignore this half of the app entirely.
The invite: no sign-up bonus
Kolan switched on referrals in its app update of 15 October 2026. Joining through an invite gives you the standard account and nothing extra: no cash, credit or fee waiver for the new customer. Open our link on your phone, install Kolan from the store page it opens, and open the app from the same phone before signing up so the invite attaches to your account. If sign-up asks for a referral code, enter KOLQRLDU.
Disclosure: the link and code KOLQRLDU are our own invite, and Kolan's Refer & Earn programme may credit us when you join and use the account. Nothing comes out of your balance.
Freezes, closures and getting your money back
Kolan's terms give it wide powers. It can limit, suspend or close an account at any time without notice, including for activity it considers suspicious, a failed identity check, or a "considerable variation" in your transaction volume up or down. You can't close the account during an investigation, and trying can get it frozen. Losses caused by a suspension aren't covered, and Kolan can set off anything it says you owe against any balance or incoming payment.
If an account is closed, Kolan may give you a reasonable window to withdraw; after that, you can still ask support to send the remaining funds by refund or bank transfer for five years. Without cause, Kolan can end the terms on 30 days' notice. Disputes go to the Delaware courts, with no class actions. In practice: keep your identity documents and invoices ready, expect source-of-funds questions after large or unusual payments, and withdraw regularly.
What users say
On 26 October 2026 Kolan scored 4.2 from about 790 reviews on Google Play, with more than 50,000 downloads, and 3.9 from 34 ratings on the US App Store; the Nigerian App Store showed 3.2 from 48. Trustpilot showed 2.4 from 8 reviews, seven of them one star, and Kolan hasn't claimed the profile or replied to any of them. Fans like the fast transfers and how easily a salary arrives.
The complaints repeat: accounts paused or frozen soon after a deposit, often citing unusual transaction patterns, with documents sent and no update; identity verification taking weeks; payments marked as on their way that didn't arrive; and support that is email only and slow or silent. One App Store reviewer reported about $15,000 stuck after a suspension. These match the powers in the terms, so plan around them.
Who should use Kolan, and who should skip it
Use it if you're paid by US clients or platforms from a country where getting dollars in is slow or expensive, you can receive in amounts above $100 so the flat fees stay small, and you'll withdraw to your own wallet or local account soon after each payment lands.
Skip it if you want somewhere safe to keep savings, need deposit insurance, rely on fast human support, mostly receive small payments under $100 by wire, or want a personal spending card. It also isn't for anyone in the UK who came for the perps or prediction markets, which the terms exclude.
FAQ
- Is there a Kolan sign-up bonus?
- No. Joining through our link or code KOLQRLDU gives you the standard account, with no cash, credit or fee waiver.
- Is Kolan the same as Hurupay?
- Yes. Hurupay Inc. renamed the app Kolan in August 2026; existing accounts, contracts and the team stayed the same.
- Is my money FDIC-insured?
- No. The website footer mentions FDIC, but the Terms of Service say funds are settled in USDC and aren't insured by the FDIC or any other deposit insurer.
- Can Kolan freeze my account?
- Yes. The terms let it suspend accounts without notice and cancel access to or confiscate funds indefinitely, without giving reasons. Withdraw regularly and keep only working balances there.
- What does it cost to receive $50 from a US client?
- $2 by ACH, leaving $48. By wire it would cost $32, because wires under $100 carry a flat $32 fee.
- How much can I receive in one payment?
- Up to $4,999 per ACH or wire payment. Payroll and platform payments from Gusto, Upwork, Rippling, Fiverr or Payoneer have no limit.
- Can I use the Kolan card for everyday shopping?
- The card terms say business use only, not personal, family or household spending. Use it for work tools and subscriptions.
- Which countries does Kolan support?
- Kolan publishes no list. Its guides target Nigeria, Kenya, the Philippines, Argentina, Pakistan and Spain, and sanctioned or crypto-banning countries are excluded; sign-up checks your country.